



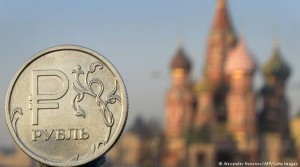
Until recently, Moscow seemed unmoved by the sanctions imposed by western powers because of the Ukrainian crisis. Now, however, the plunge in oil prices and the subsequent free-fall of the ruble have put the Russian government on alert.
Following a 20% drop on Monday, the Russian ruble began to recover against the US dollar and euro earlier today, after Russia’s foreign ministry announced that it was selling foreign exchange.
More specifically, according to Bloomberg, the ruble strengthened 6.8% to 63.2230 a dollar after the Ministry’s announcement.
It should be noted that yesterday the ruble sank beyond 80 per dollar, after a surprise interest rate hike failed to stop the currency’s crash.
In the meantime, many Russians are demonstrating a somewhat paradoxical reaction to the recent financial developments in their country, by going on a shopping spree.
A large part of the country’s population are rushing to the stores to buy electronics, cars and other imported items before the inevitable inflation’s rise that will cause prices to soar.
According to Igor Nikolayev, head of the FBK Strategic Analysis Institute, this phenomenon will last another couple of months, until people have spent all their savings. Then, “the most difficult period begins,” he said.
Ask me anything
Explore related questions