



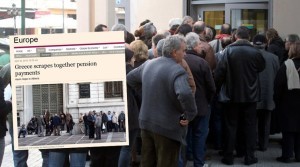
Financial Times was the latest to pick up on the long lines that formed earlier in the week outside ATMs in mostly central Athens area locations, taking note of the fact that most of the people in line were …grey haired.
As reported on Tuesday evening by Proto Thema, payments by Greece’s biggest pension fund, the state-run IKA, hadn’t been credited to accounts on Tuesday afternoon, as expected. The government later cited a “technical glitch”, promising that payments would be made on Wednesday, something that was proven true.
Anxious depositors and retirees have obviously been influenced by rampant speculation, in large part media driven, that the leftist government in Athens has run out of cash.
Of course, reports, media speculation, rumours, analyses and conjecture of a PSI “haircut” proved true in 2012, when private sector bond holders of Greek securities took a massive hit. That development was followed a year later by the “haircut” and capital controls endured by depositors of Cypriot banks, during the island republic’s financial crisis and eventual bailout in 2013.
FT quoted Dimitris Stratoulis, the deputy minister for social security, who cited the “technical problem” with the inter-bank payment system as causing the delay.
Meanwhile, as the Greek government apparently made its salary and pension payments this week, Reuters reports that the country’s next payment to the IMF comes on May 6, to the tune of 200 million euros in interest payments.
An IMF spokesman on Thursday added the organization was awaiting a “detailed” assessment of Greece’s liquidity situation over the next few days.
The next IMF payment comes on May 12 — 750 million euros.
Ask me anything
Explore related questions