



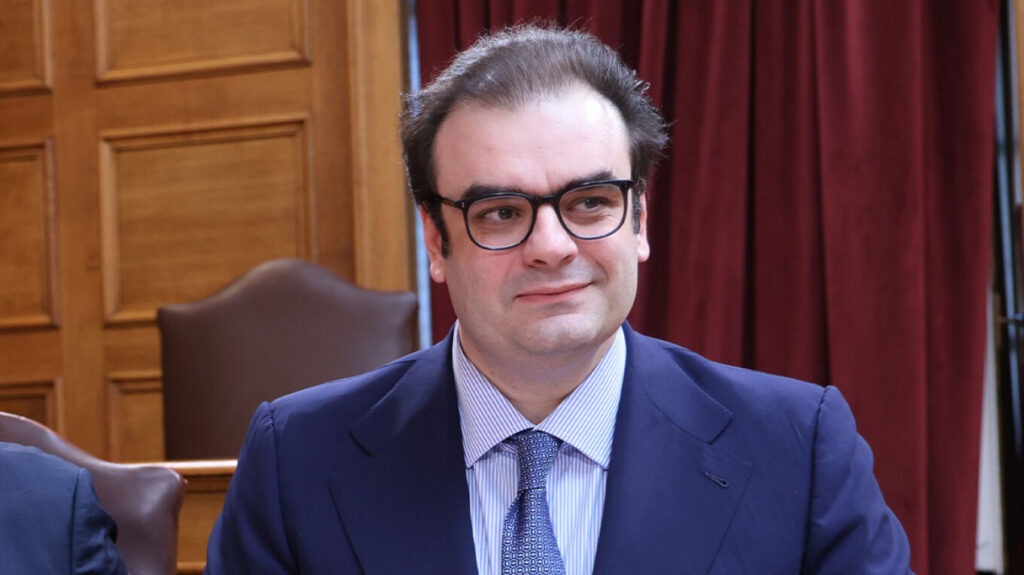
Greece is introducing a fixed 3% interest rate for eligible borrowers entering debt restructuring agreements through its out-of-court settlement mechanism, while increasing the maximum fines imposed on loan servicing companies tenfold, Finance Minister Kyriakos Pierrakakis announced in parliament on Tuesday.
The two measures will be introduced as amendments to legislation aimed at protecting borrowers and tightening oversight of companies managing outstanding loans, including those transferred by banks to investment funds.
Speaking before the relevant parliamentary committee, Pierrakakis said the government was seeking to reduce repayment costs, provide greater certainty for households and strengthen penalties against loan servicers that fail to comply with their legal obligations.
The proposed legislation already includes 16 provisions concerning borrowers’ rights and debt management. It is scheduled to be debated and voted on in parliament’s plenary session on Wednesday.
Fixed 3% Interest Rate Throughout Repayment Period
The first amendment introduces a fixed annual interest rate of 3% for vulnerable and eligible borrowers who restructure debts owed to financial institutions through Greece’s out-of-court settlement mechanism.
The measure covers borrowers officially classified as vulnerable under Greek legislation, as well as those meeting broader eligibility criteria that, according to the minister, extend protection to middle-income households.
Under the existing framework, loans secured against property carry an interest rate of 3% for the first three years, while unsecured debts are subject to a 4% rate over the same period.
After the initial three years, interest rates become variable and are linked to the three-month Euribor benchmark, with additional margins of 2.5 percentage points for secured debts and three percentage points for unsecured debts.
At the Euribor level of 2.67% cited by the minister, this would translate into interest rates of 5.17% and 5.67%, respectively.
The new arrangement eliminates these subsequent increases for eligible borrowers, maintaining the 3% rate throughout the entire restructuring agreement, regardless of whether the debt is secured against property or which financial institution holds the claim.
The fixed rate will become a mandatory contractual condition and will apply to payments from 1 December 2026.
According to Pierrakakis, this will allow borrowers to calculate their monthly repayments with greater certainty and avoid the risk of rising instalments as market interest rates fluctuate.
Savings of Up to €28,600 on a €100,000 Debt
The finance minister presented examples illustrating the potential financial benefits of the proposed changes.
For a €100,000 debt restructured over 20 years, equivalent to 240 monthly instalments, the government estimates that maintaining a fixed 3% interest rate could generate substantial savings compared with the current variable-rate system.
For a secured debt, the total estimated benefit would reach approximately €20,200.
For an unsecured debt of the same amount and repayment duration, savings could increase to approximately €28,600.
The calculations assume the current Euribor rate and a repayment structure without the gradual instalment increases associated with the so-called step-up mechanism.
The actual financial benefit would depend on the terms of each restructuring agreement and future interest rate movements.
Pierrakakis stressed that the measure was not limited to the most financially vulnerable households, but would also benefit eligible middle-income borrowers seeking more manageable repayment arrangements.
Maximum Fines for Loan Servicers Rise to €5 Million
The second amendment substantially increases the financial penalties that the Bank of Greece can impose on loan servicing companies for serious regulatory breaches.
Under the existing framework, the maximum administrative fine stands at €500,000. The proposed legislation raises that ceiling to €5 million, representing a tenfold increase.
The higher penalties will apply to a range of violations involving the management of outstanding debts and the treatment of borrowers.
These include failures to maintain appropriate internal governance and compliance procedures, inadequate handling of borrowers’ complaints, breaches of personal data protection requirements and failures to fulfil obligations concerning information provided to borrowers.
The measures also cover violations relating to contractual arrangements between credit purchasers and servicing companies, outsourcing activities and requirements governing the transfer and management of loan portfolios.
According to the finance minister, the increased penalties are designed to make non-compliance considerably more costly for companies operating in Greece’s debt management sector.
The Bank of Greece will remain responsible for imposing these sanctions under the relevant supervisory legislation.
The minister also clarified that the new €5 million ceiling is separate from penalties already included in the bill.
Those provisions allow fines ranging from €50,000 to €500,000 per borrower in certain cases where collection action is taken against a borrower who is meeting repayment obligations, or where missed payments result from a creditor’s or servicer’s failure to provide necessary information.
Government Defends Bill Against Opposition Criticism
The announcements came amid a heated parliamentary debate over the government’s proposed changes to the regulation of private debt and loan management companies.
Opposition parties, including PASOK and SYRIZA, have accused the government of introducing provisions that could favour loan servicers rather than strengthen borrowers’ protections.
Pierrakakis rejected those allegations, arguing that the expanded regulatory obligations and substantially higher financial penalties demonstrated the government’s intention to hold servicing companies accountable.
He also addressed criticism surrounding Article 23 of the draft legislation, which had attracted objections from opposition parties and legal professional associations.
According to the minister, the provision concerned restructuring arrangements agreed by mutual consent between borrowers and loan managers. He maintained that it did not authorise servicers to alter loan agreements unilaterally.
Nevertheless, the government withdrew the provision following the controversy.
Pierrakakis said the withdrawal was intended to remove an obstacle to opposition support for the remaining legislation.
Pierrakakis Challenges Tsipras Over Loan Sales to Funds
The finance minister also criticised former prime minister Alexis Tsipras over comments concerning the introduction of loan servicing companies and investment funds during Greece’s financial crisis.
Tsipras had argued that the regulatory framework enabling the operation of funds and servicers was introduced under pressure from international creditors in December 2015, but maintained that no loans had been transferred from banks to funds during his premiership.
Pierrakakis disputed that account, citing Bank of Greece figures which, he said, showed that by the end of March 2019 companies had assumed responsibility for loans with total claims of €18 billion and a gross book value of €8.5 billion.
He argued that the figures contradicted the former prime minister’s account of developments during his administration.
The minister also challenged PASOK to support the legislation, accusing the opposition party of favouring political criticism over practical solutions for indebted households.
The two new amendments form part of the government’s broader effort to address Greece’s private debt burden, improve the operation of its out-of-court restructuring mechanism and increase regulatory scrutiny of the companies responsible for managing outstanding loans.
With the parliamentary vote approaching, the central measures are the proposed fixed 3% rate for qualifying borrowers and significantly tougher sanctions against loan servicers that breach their obligations.
Ask me anything
Explore related questions